Sales confirmed just had its worst month yet. Here's why September decides the rest of the year.
September was the test. The numbers are in, and the answer is clear.
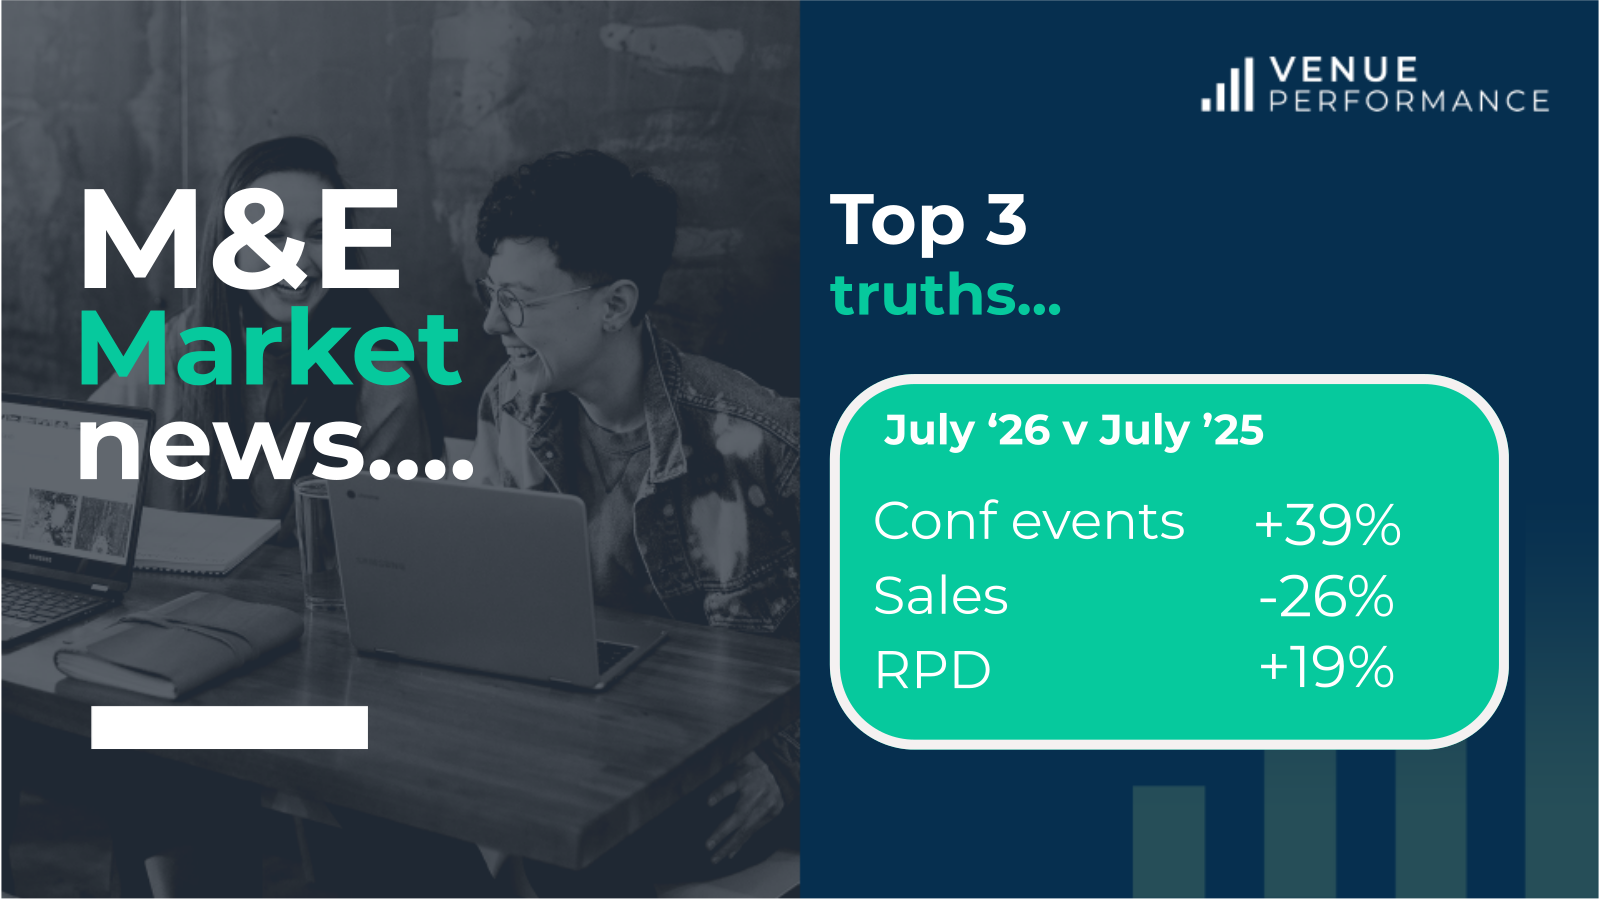
Sales confirmed fell 26% in September, year-on-year.
That’s the fifth month running, and each month has been deeper than the last: May -11.3%, June -20.4%, July -23.7%, August -24.4%, September -26.4%. (August has settled at -24.4% now the final data is in.)
But that’s not the whole picture.
- RPD grew 26.1% in September, its strongest month of the year, reaching £150.68 per delegate.
- Enquiries dipped 1.0%, a second month below last year.
One line at a high, one at a low, and demand flattening in between.
Zoom out to the full year: enquiries are up 10.4%, events delivered up 7.3% and RPD up 14.4%.
Sales confirmed is now down 7.4% year-to-date.
The yield story keeps getting stronger
September’s RPD growth came alongside a 17.4% rise in delegation size, so this isn’t dilution: venues earned more per head on bigger events. F&B is doing most of the lifting, up 36% in the month and 25% year-to-date.
Introducing RevMet™
This month we’re adding a new metric: RevMet, revenue per available metre. It’s the meetings and events equivalent of RevPAR, showing how hard meeting space is working in a single number.
The first UK read is striking. Year-to-date RevMet is £1,223 against £794 last year, up 54%. September alone was up 43%, and every month of 2026 has beaten its 2025 equivalent.
August barely moved, as you’d expect in the quietest month of the year.
Meetings and Conferences: same pattern, different timing
Meetings is where the pressure sits.
- Enquiries fell 20.8% in September, the steepest drop of the year.
- Sales confirmed has fallen every month since May and is down 10.9% YTD.
- RPD is still up 12% year-to-date with delegation size flat, so that growth is rate, led by room hire.
Conferences have carried 2026.
- Events delivered are up 47.9% year-to-date and have risen in every month.
- But sales confirmed has been negative since July, falling 17% in September, even as enquiries rose 17%.
More enquiries, fewer conversions. And September is a full month, so this can’t be put down to a thin base.
Put simply, the slowdown started in short-lead meetings in May and reached conferences by July.
One more thing worth knowing: UK-wide RPD growth (14.4%) is higher than either segment on its own (Meetings 12.0%, Conferences 9.8%). That’s mix. Conferences have grown from 26% to 35% of events, and they carry higher yield per delegate.
What this means for you
- September confirmed the trend rather than breaking it. Q4 planning has a clearer signal than it did a month ago.
- If you’re meetings-heavy, the decline is broad, accelerating and now five months long.
- If you’re conference-heavy, volume is still strong, but conversion is slipping.
- Yield is carrying performance. The question is how long rate holds if demand keeps softening.
- Lead times are lengthening: 38.8 days in September, up from 30.4. Pipeline views need to look further out.
As always, every venue’s mix is different. These are national figures, and where you land depends on your own segment split, region and positioning.
This data comes directly from member venues’ actual booking systems - not surveys or estimates. If you want to see how your own venue compares, and you’re not using Venue Performance, get in touch - the devil always lurks in the detail.
Join our monthly M&E Insights webinar for more detail on Friday 23rd October at 12 - REGISTER HERE
So if you want to see how your own venue compares, and you're not using Venue Performance, get in touch - the devil always lurks in the detail.